Commercial Roof Insurance Claim Assistance in Milwaukee, WI
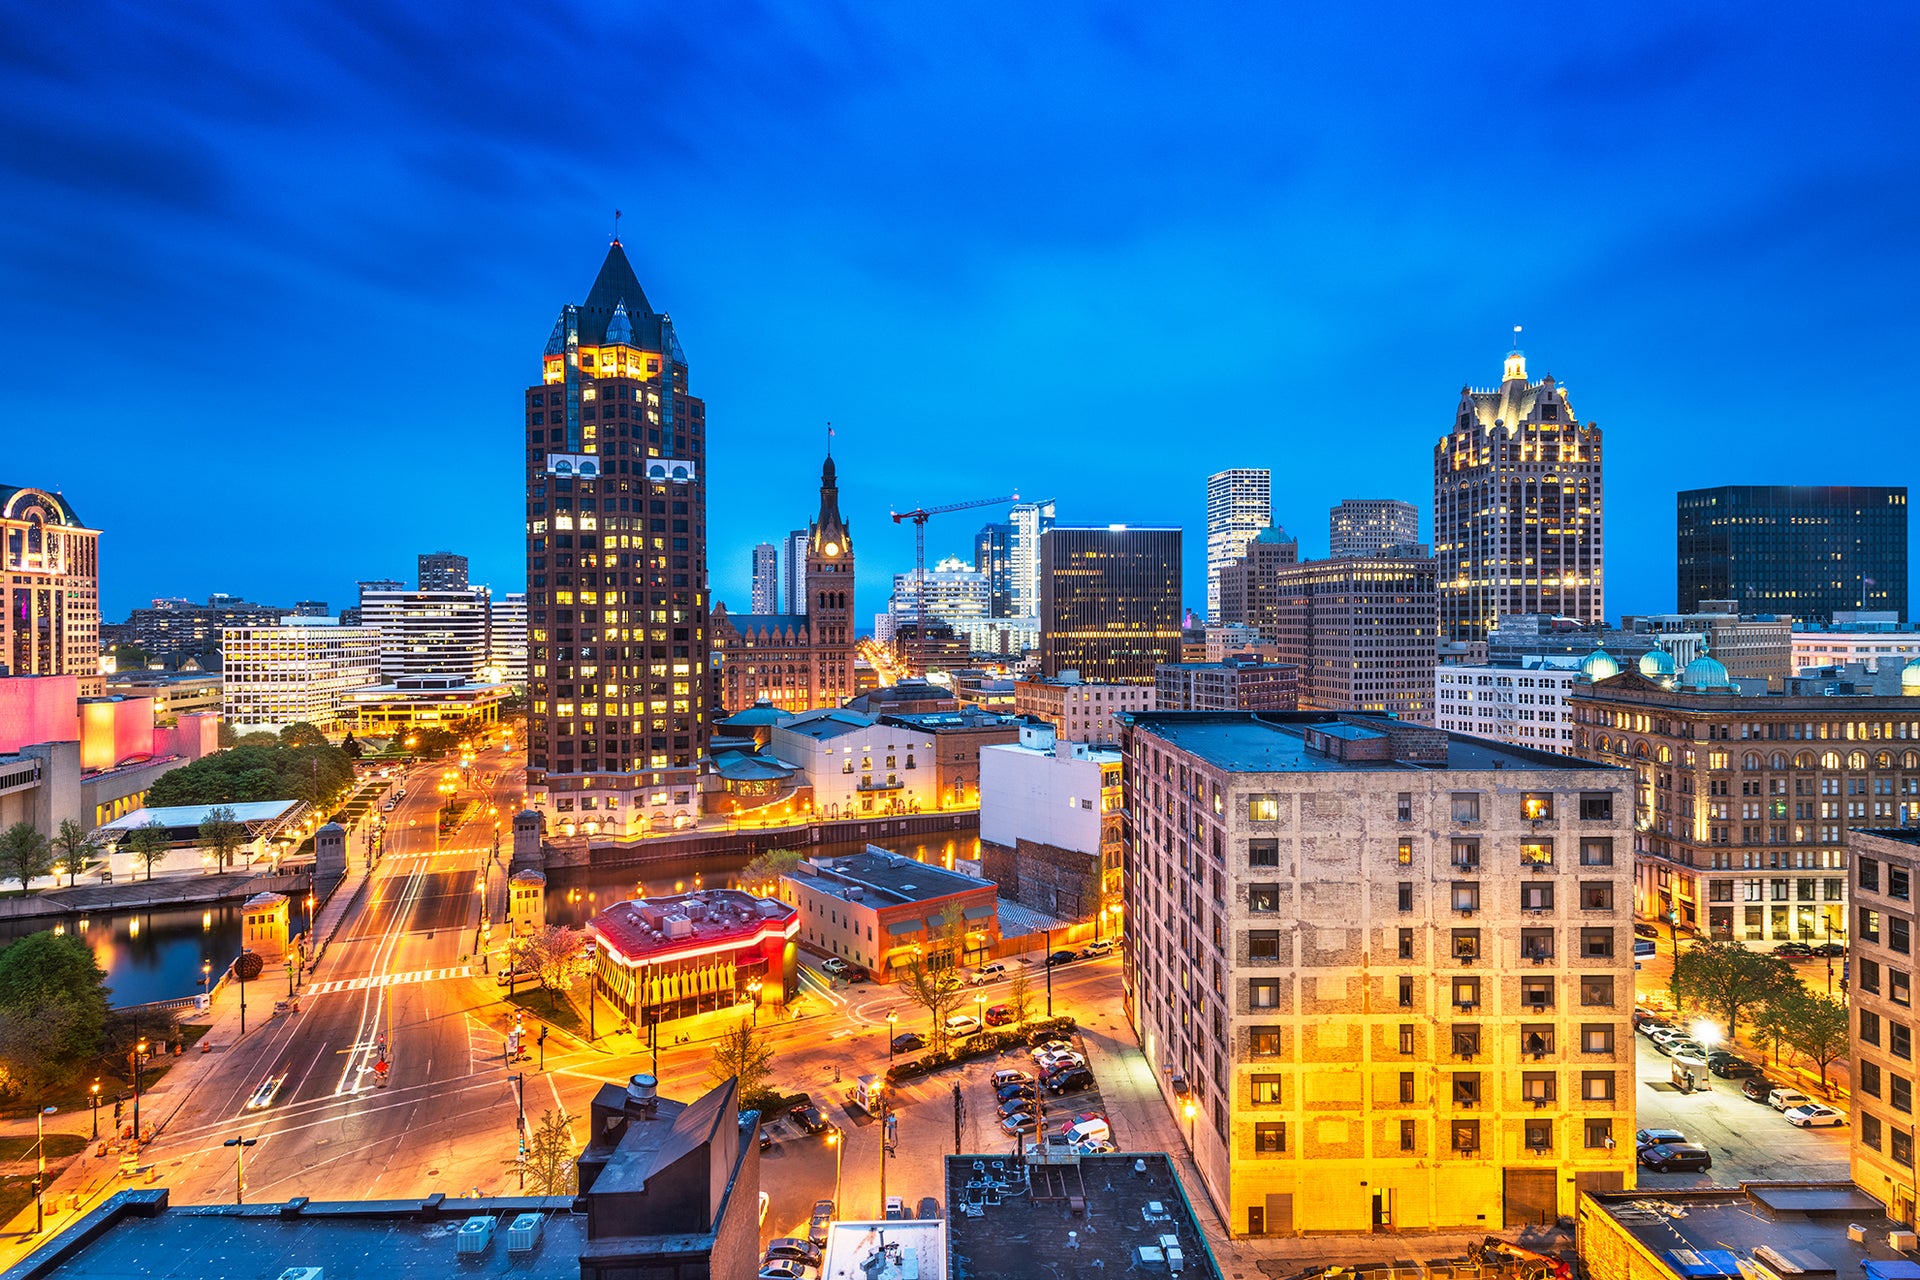
When a Milwaukee commercial roof takes wind, hail, or ice damage, the claim goes only as far as the documentation behind it. We inspect, measure, and photograph the roof so you and your adjuster are working from the same facts.
The roofs that generate the most confusing claims in this city are not the newest ones. A Third Ward building with a mid-2000s adaptive reuse re-roof over old brewery-era masonry, a Menomonee Valley warehouse with three membrane generations stacked under the current cap sheet, a strip retail roof with a patched-over EPDM field — each of these has a history that an adjuster can't read from the ground. Our job before anyone talks settlement numbers is to put that history, and the fresh damage, in writing.
What we actually do on a claim
We are a roofing contractor, not a public adjuster, and the claims work we do reflects that. We climb the roof, photograph every point of damage, measure hail bruising and displaced panels, probe for wet insulation, and note where flashing, coping, or drains were compromised. That becomes a written scope: what's damaged, what code requires when that area is opened up, and what it takes to bring the roof back to a uniform, warrantable condition. What we don't do is file the claim on your behalf, negotiate the settlement, or promise a payout number — that's between you, your broker, and the carrier.
Meeting the adjuster on the roof
A carrier's adjuster typically sees the roof once, often on a schedule that doesn't match the building owner's. We try to be there for that visit with our own documentation already assembled — same damage points, same measurements, same photos — so the walk becomes a comparison of notes instead of a first look. On a low-slope roof with membrane seams, mechanical curbs, and parapet walls, a lot of real damage is easy to miss from a quick pass, and we've found that a documented starting point changes how thorough that visit ends up being.
Framing the complete scope
Milwaukee's older commercial stock adds real cost to a "like for like" repair estimate. A parapet wall on a converted warehouse near the Valley may need matching coping that isn't stocked anymore. A partial hail-damaged field on a BUR or modified bitumen roof usually can't be patched into a single membrane generation without new problems. And current code often requires insulation upgrades or drainage corrections the moment a roof section is opened for repair. We put those items in the scope explicitly — not to inflate it, but so nothing legitimate gets left out because it wasn't obvious from a drive-by.
When a claim comes back short
Denials and underpaid scopes happen for reasons that are often fixable: the adjuster didn't get on the roof long enough, the damage was described as cosmetic when it was functional, or the estimate didn't account for code-required work triggered by the repair itself. When that happens, we can go back up, re-document with more detail, and put together a supplemental report the owner can hand to their broker or carrier. We're your roofing contractor, not a public adjuster — we document and substantiate the roof damage so you and your adjuster work from an accurate scope, and what happens with that report afterward is the owner's call.
If a storm, hailstorm, or heavy ice season has left a Milwaukee commercial roof with visible or suspected damage, the roof should be inspected and documented before repairs start or a claim gets filed. Reach out with the address, the type of loss, and photos if you already have them, and we'll get a documented inspection scheduled.
Questions owners ask
Does insurance cover commercial roof replacement in Milwaukee?
It depends on the policy and cause of loss. Wind, hail, and sudden weight-of-ice or weight-of-snow damage are commonly covered; wear, age, and deferred maintenance usually are not. A documented inspection helps show which category applies.
What does the commercial roof insurance claim process look like?
Report the loss, get the roof inspected and documented, meet the adjuster on the roof with that documentation, then review the resulting scope against what the inspection found.
What if a claim comes back denied or underpaid?
A denial or a scope that leaves out flashing, insulation, or code-required work isn't always final. A supplemental inspection report documenting what was missed gives the owner something concrete to bring back to the carrier.
Should we repair or replace after storm damage?
That depends on the roof's age, how much area is affected, and whether the membrane and insulation are sound underneath the damage. A field inspection with photos and measurements makes that call defensible either way.
Who meets the insurance adjuster at the building?
We do, as the roofing contractor, walking the adjuster through the same damage points, measurements, and photos already on file.
Do you negotiate the settlement with our insurance company?
No. We document and substantiate the roof damage so you and your adjuster work from an accurate scope; negotiating the claim itself stays between you, your broker, and the carrier.
Share the roof address, the type of loss, and any photos you already have. We'll schedule a documented inspection and, if there's active water entry, talk through emergency dry-in first.
Related roof pages
Hail Damage Roof Insurance Claims in Milwaukee, WI
Documentation for hail-bruised membranes and metal after a southeastern Wisconsin hailstorm.
Wind and Storm Damage Roof Insurance Claims in Milwaukee, WI
Documentation for wind-lifted membrane and displaced metal after severe Milwaukee storms.
Snow and Ice Roof Damage Insurance Claims in Milwaukee, WI
Documentation for ice-dam and snow-load damage after a hard Milwaukee winter.
Insurance Claim Roof Documentation in Milwaukee, WI
The photo, measurement, and repair-note file that supports a Milwaukee commercial roof claim.
Commercial Roof Leak Repair in Milwaukee, WI
Commercial Roof Leak Repair for Milwaukee commercial buildings.
Emergency Tarp Dry In in Milwaukee, WI
Fast temporary dry-in after storm damage to stop interior loss while a claim moves forward.